
If you're planning to purchase a home as a military family, you are likely tracking VA loan eligibility and VA loan requirements. But, as you begin your research, you will inevitably come across a critical acronym that can make or break closing a VA loan: MPRs.
MPRs are short for Minimum Property Requirements, but what are they, why do they exist, and what do they mean for you in the home-buying process? Let’s break down the basics so you can tour homes and prepare to make an offer with confidence.
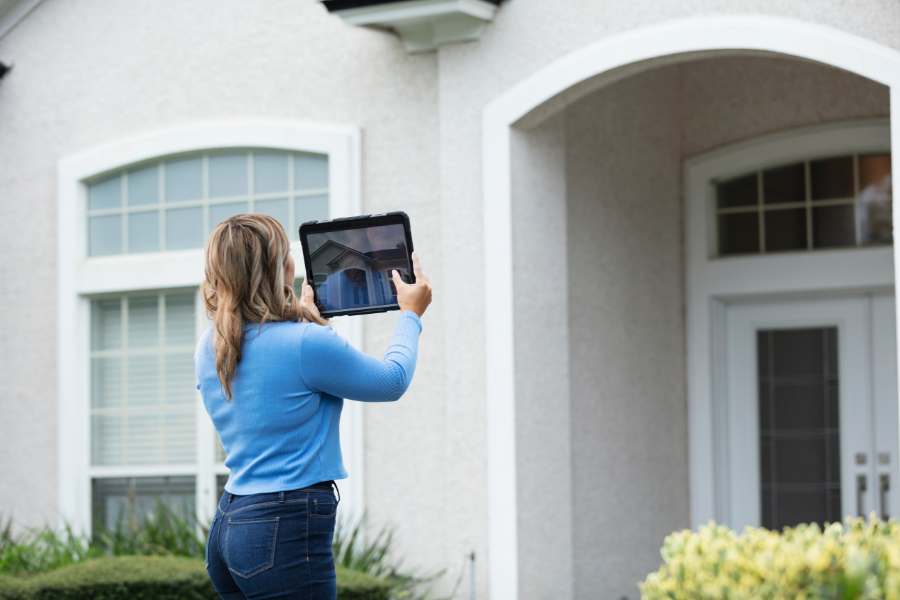 Photo by kali9 from Getty Images Signature via Canva.com
What Are VA Minimum Property Requirements?
At its core, the Department of Veterans Affairs wants to ensure that military home buyers are moving into homes that are safe, structurally sound, and sanitary. Minimum Property Requirements (MPRs) are baseline health and safety standards established by the VA to help protect military buyers from inadvertently purchasing a money pit.
Unlike a conventional mortgage, where a lender’s appraisal primarily focuses on the home’s financial evaluation, a VA-backed loan requires an appraisal that evaluates both fair market value and adherence to these MPRs.
A good way to think of MPRs is as an extra layer of protection for military families. They ensure the safety and functionality of the home, such as a working heating system, clean water and working plumbing systems, a solid roof, and freedom from environmental hazards.
Before you close on a home using the VA loan, a VA appraisal must occur, and MPRs will be evaluated as part of that process.
What Can Cause a Home to Fail a VA Appraisal?
It's possible for a home to fail a VA appraisal. A number of factors might result in a failed appraisal, including the following.
Peeling or Chipped Paint
For homes built before 1978, chipped or peeling paint is an automatic violation because of lead-based paint hazards. This applies to indoor walls, outdoor siding, windowsills, porch railings, and even detached sheds or carports.
Issues with the Roof
A roof must have a reasonable life expectancy left, typically at least three years. Missing shingles, active leaks, or multiple layered roofs (for instance, old patchwork or new shingles layered on top of an older roof) will flag a failure.
Heating and Cooling Systems
The home must have a safe, permanently installed HVAC system capable of maintaining comfortable and safe heating. Space heaters or unvented stoves do not qualify. Interestingly enough, there are no VA MPRs for air conditioning, regardless of the climate. However, if a system is installed, it must be operational and working properly.
Water and Plumbing
The property must have continuous access to safe, drinkable water, functional hot water heaters, and adequate sewage disposal.
Wood Damage and Wood-Destroying Insects
Evidence of termites, carpenter ants, and dry rot will quickly bring a VA appraisal to a screeching halt. If dry rot or wood-destroying insect damage is visible, the issue must be treated and repaired before closing.
Safe Access and Hazards
The property must have safe, private access from a public or private street. Proximity to environmental hazards, like high-voltage power lines or routine flood zones, can also trigger issues.
What if a home gets flagged?
An MPR flag doesn’t automatically kill the deal. The seller can complete the repairs before closing, or, in some instances, the buyer and seller can agree to an escrow holdback, in which the seller offers repair funds set aside during the closing process.
Sometimes, a buyer may offer to complete and pay for some repairs independently prior to closing, such as painting porch railings or exterior windowsills, and request a re-appraisal to meet MPRs and successfully generate the VA loan.
Can You Buy a Fixer-Upper with a VA Loan?
The short answer? It depends on your definition of a "fixer-upper."
If your version of a fixer-upper is a cosmetic makeover, complete with outdated avocado-green shag carpet, 1980s wallpaper, original kitchen cabinets, and wood paneling, you can absolutely buy it using a standard VA loan. The VA doesn't care if the home is outdated, provided the mechanical systems, structure, and safety can pass appraisal.
However, if your vision of a little "sweat equity" is a caved-in roof, non-functioning plumbing, or missing drywall, these issues will absolutely not clear a VA appraisal. The home must meet MPRs at the time of closing.
For buyers with the ability or willingness to undertake major structural renovations, an option is the VA Rehabilitation Mortgage, or VA Renovation loan. This specialized loan lets you roll the purchase price and qualified renovation costs into a single mortgage. However, keep in mind that not all lenders offer this option, and it requires a fair amount of work to identify approved contractors and create detailed project timelines.
What’s the Difference Between a VA Appraisal and a Home Inspection?
If there is one takeaway, it is this: a VA appraisal identifying MPRs is not the equivalent of a private buyer's home inspection.
While a VA appraiser will note obvious defects, like a damaged roof or peeling paint, they aren't crawling into tight attics or crawlspaces or testing individual electrical outlets. A licensed home inspector works solely for the buyer, to provide a comprehensive report on both minor and major repairs and issues, and to identify any hidden flaws that an appraiser might miss.
Pro tip: Getting a buyer’s inspection before the VA appraisal is an excellent strategy to highlight any glaring issues that will be identified during the appraisal and offer both buyer and seller additional time to reach a solution in order to close the sale.
In Summary
Understanding the purpose of MPRs is just one piece of the puzzle for putting your VA home loan benefits to work. With an understanding of MPRs, you can evaluate listings confidently and submit realistic offers by identifying potential issues during a VA appraisal, preventing unexpected closing delays.